

Table of Contents
- Why Most Kitchen Remodel Budgets Fail
- How to Determine Your Average Cost of Kitchen Remodel
- Build a 15-20% Contingency Fund Before You Demo
- How to Save Money on Kitchen Cabinets Without Sacrificing Looks
- The Real Kitchen Renovation Timeline (and Why It Affects Your Budget)
- Financing and Payment Strategies That Protect Your Wallet
- Resale Value ROI: Which Upgrades Pay You Back
- Supply Chain and Material Lead Times: The Hidden Budget Killer
- Frequently Asked Questions
Last Updated: September 23, 2026
Why Most Kitchen Remodel Budgets Fail
A kitchen remodel budget fails when it plans for the finished room but not the process. Demolition uncovers problems, materials arrive late, and change orders pile up.
How to Determine Your Average Cost of Kitchen Remodel
The average cost of kitchen remodel depends on scope, materials, and labor. The gap between mid-range and upscale work grows fast once you touch plumbing, electrical, or structural elements.
Minor vs. Major vs. Upscale: What Changes the Price
A minor remodel keeps the existing layout and refreshes surfaces: paint, hardware, a backsplash, maybe a countertop swap. A major remodel moves walls, relocates plumbing and electrical, and replaces cabinetry and appliances. An upscale renovation adds custom millwork, high-end countertops, and structural changes.
| Project Scope | What Changes | Budget Driver |
|---|---|---|
| Minor refresh | Paint, hardware, backsplash | Material expenses only |
| Major remodel | Layout, plumbing, electrical | Labor costs and permits |
| Upscale renovation | Custom cabinetry, structural work | Design fees and finishes |
Build a 15-20% Contingency Fund Before You Demo
A contingency fund of 15-20% of your total project cost is the most effective protection against a blown kitchen remodel budget. It absorbs hidden structural issues, code corrections, and mid-project changes without forcing you to cut quality elsewhere.
How to Save Money on Kitchen Cabinets Without Sacrificing Looks
Cabinet costs are the largest single line in most kitchen remodel budgets, and the easiest to reduce without a visible downgrade. Refacing, painting, and open shelving cut material expenses while keeping the room looking intentional.
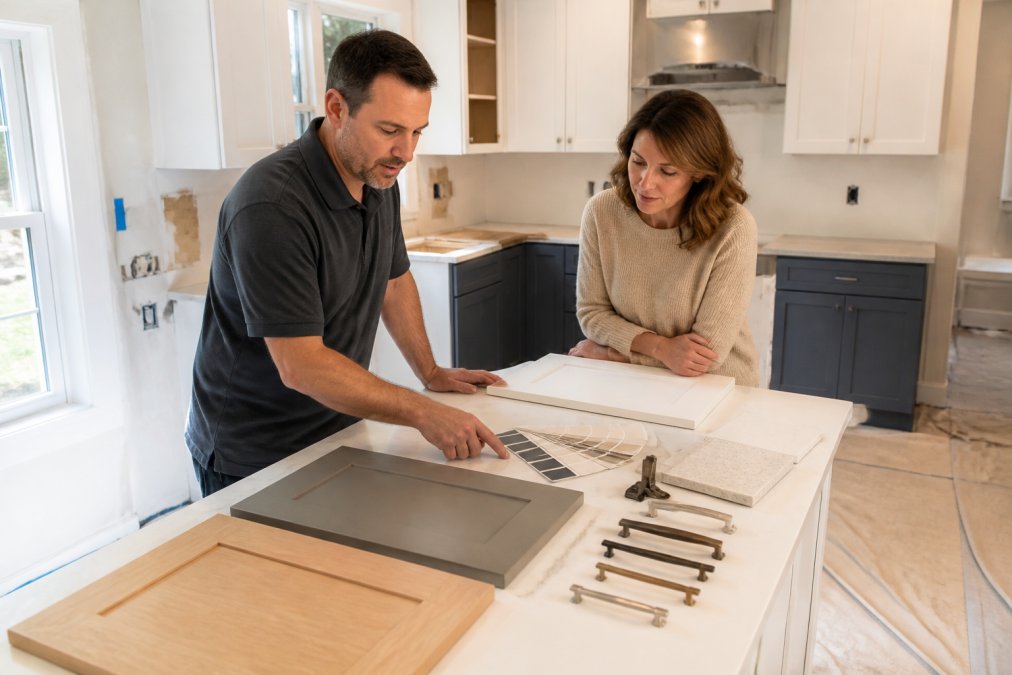
Refacing, Painting, and Open Shelving: Where the Savings Are
- Refacing: New doors and veneer over existing boxes. Keeps the layout, cuts material cost.
- Painting: A fraction of replacement cost. Best for cabinets in good structural shape.
- Open shelving: Removes upper cabinet expense entirely and opens the kitchen footprint.
- Hardware swaps: New pulls and hinges change the look for very little.
Open shelving only saves money if you're comfortable losing closed storage. For heavy cooks, that trade rarely pays off.
The Real Kitchen Renovation Timeline (and Why It Affects Your Budget)
Plan around material arrival, not when you'd like work to start. Sequencing the schedule around lead times is how a kitchen remodel budget stays intact.
Financing and Payment Strategies That Protect Your Wallet
How you pay matters as much as how much you spend. "Consider a home equity loan" is useless without the terms, trade-offs, and payment mechanics that decide whether a project finishes on budget or stalls halfway through.
Matching the Financing Tool to the Project
There's no single best way to fund a kitchen. The right tool depends on how long you need the money, how much equity you have, and whether you can tolerate a variable rate.
- Home equity line of credit (HELOC): A revolving line secured by your home. You draw only what you need, which suits phased projects where costs land in waves. Most HELOCs carry a variable rate tied to the prime rate, so your payment can move. A common pattern is a draw period followed by a repayment period, which means the full balance comes due on a set schedule.
- Home equity loan: A lump sum at a fixed rate, repaid in equal installments. Predictable, but you pay interest on the entire amount from day one even if your contractor doesn't need it until month three.
- Cash-out refinance: Replaces your existing mortgage with a larger one and hands you the difference in cash. This can work when current mortgage rates are at or below your existing rate, but it resets your entire loan term and closing costs apply. If your current rate is well below today's market, this is usually the wrong move.
- Personal loan or contractor financing: Unsecured, faster to obtain, and not tied to your home. Rates run higher than secured options, and loan amounts are typically smaller. Contractor-offered financing can be convenient but read the terms, promotional rates often jump sharply after an introductory period.
The Payment Schedule That Protects You
Never pay a contractor the full amount upfront. Structure payments around milestones, holding the final payment until the scope of work is complete and inspected.
A common approach looks like this:
Call the Expert Renovation Contractors Now →
- Deposit at contract signing, enough to cover initial material orders, not the whole job.
- Draw at rough-in completion, after framing, plumbing, and electrical pass inspection.
- Draw at cabinet and countertop installation, when the bulk of materials are set.
- Final payment at walkthrough, released only after punch-list items are corrected and you've signed off.
Phasing as a Cash-Flow Strategy
If financing isn't attractive or you'd rather avoid debt, phasing across two budget cycles is legitimate. Split the work into a "must-do now" phase (layout, plumbing, electrical, cabinetry) and a "later" phase (backsplash, lighting, built-ins).
Resale Value ROI: Which Upgrades Pay You Back
Not every dollar you spend on a kitchen comes back at resale. The cost-to-value ratio varies widely by upgrade, and the highest-cost items are rarely the highest-return ones.
Upgrades That Tend to Recoup the Most
These are the items buyers consistently pay for, because they read as "updated" and "functional" rather than "custom":
- Refinished or refaced cabinetry. New doors, drawer fronts, and hardware over solid existing boxes deliver a visible transformation at a fraction of full replacement cost. Buyers see a new kitchen; you paid for a facelift.
- Mid-range countertops. Quartz and quality laminate in a neutral tone photograph well and hold up. Exotic stone in a bold pattern narrows your buyer pool without adding proportional value.
- Updated lighting. Recessed cans, under-cabinet task lighting, and a statement fixture over an island are inexpensive relative to cabinetry and dramatically change how a kitchen feels in listing photos.
- Functional layout improvements. A better work triangle, added counter space, or a relocated sink that improves flow appeals to nearly every buyer. Layout is the one upgrade that can't be replicated with paint.
- Energy-efficient appliances. Standard-depth, Energy Star-rated appliances appeal to buyers and can reduce utility costs, which is a selling point in a competitive market.
Upgrades That Rarely Pay You Back
These are the items where cost and return diverge sharply:
- Custom millwork and built-ins. Beautiful, but priced for you, not for the next owner. A buyer with different taste sees a renovation they'd want to redo.
- High-end professional-grade appliances. A commercial range in a standard home rarely returns its cost. Buyers who want that equipment usually want it in a home priced to match.
- Bold or highly personal finishes. Statement tile, unusual cabinet colors, and niche layouts can actually reduce your buyer pool.
- Structural changes with no functional payoff. Moving a wall for aesthetics alone is expensive and rarely recouped.
- Luxury add-ons. Wine refrigerators, built-in coffee systems, and warming drawers are lifestyle purchases, not value drivers.
How to Weight Your Budget for Resale
If resale value is a real goal, weight your budget toward layout function, lighting, and durable finishes, and skip custom flourishes that appeal to a narrow set of buyers. A well-executed mid-range remodel usually returns more than chasing an upscale look.
The Bottom Line on ROI
Treat ROI as a tiebreaker, not a budget driver. If you'll stay for years, prioritize what you'll enjoy daily. If you may sell soon, prioritize the recoup-heavy list above and defer the rest. Either way, functional, neutral upgrades outperform expensive, personal ones at resale.
Supply Chain and Material Lead Times: The Hidden Budget Killer
Material lead times are the most under-planned cost in kitchen renovation, and they hit every budget line at once. When cabinets arrive late, labor reschedules, storage costs climb, and the project timeline stretches. None of that shows up on a quote.
Frequently Asked Questions
What is a realistic budget for a kitchen remodel?
A realistic kitchen remodel budget depends on scope, size, and material choices. A minor refresh with paint, new hardware, and updated fixtures costs far less than a full gut renovation with structural changes, new cabinetry, and high-end finishes. Most homeowners should plan for a 15-20% contingency on top of their working number. Getting at least three contractor quotes based on a written scope of work is the only way to know what your specific project will cost. Contact a local remodeling contractor for a detailed estimate.
What is the 30% rule in remodeling?
The 30% rule in remodeling is a guideline suggesting you should not spend more than 30% of your home's value on a renovation project. For a kitchen remodel, this helps prevent over-improving for the neighborhood. If your home is worth $400,000, a kitchen remodel above $120,000 may not return its cost at resale. This rule is a starting point, not a hard limit. Homeowners planning to stay long-term may justify spending more for personal enjoyment, while those selling soon should weigh every dollar against expected resale value.
Is $10,000 enough to renovate a kitchen?
A $10,000 kitchen renovation is possible for a cosmetic refresh, but not for a full remodel. At that budget, you are looking at painting cabinets, replacing hardware, upgrading a faucet, and possibly new countertops on existing bases. Structural changes, new cabinetry, plumbing relocations, and appliance packages will push costs well beyond $10,000. If your budget is fixed at that level, prioritize the changes that affect daily function and visual impact most, and skip anything requiring permits or subcontractors.
How do you prioritize spending during a kitchen renovation?
Prioritize spending on elements that are hardest to change later: layout, plumbing, electrical, and cabinetry. These involve demolition, permits, and subcontractors, so getting them right the first time saves money. Fixtures and finishes like lighting, backsplash, and paint are easier to upgrade down the road. Spend on the kitchen footprint and structural work first, then allocate remaining funds to countertop materials, flooring, and appliance package choices. This phased approach keeps your project functional and on budget.
Comments